Right now, a number from America is quietly pushing and pulling at your stock portfolio. That number is the US 10-year Treasury yield, and it is currently trading above 5 percent, its highest level since 2002. If you do not follow US markets closely, this sentence may not mean much to you. But this single number is one of the big reasons Indian markets have been under pressure lately, with foreign investors pulling money out and the Nifty going through its longest falling streak since the COVID crash. Let us break this down slowly, in simple words, so you understand exactly how it reaches your portfolio.
What is a bond, and what is a bond yield
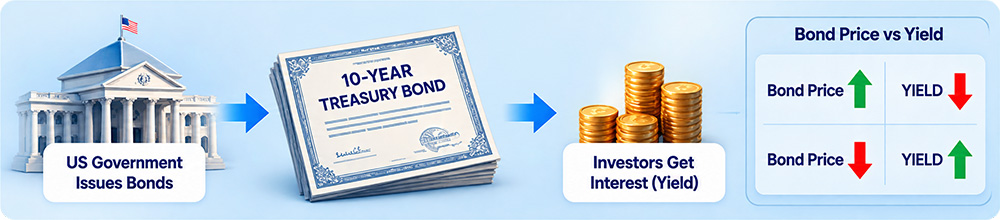
Think of a bond as a loan. When the US government needs to borrow money, it issues bonds. This means it borrows money from investors and promises to pay them back, with some extra interest, over a fixed number of years. A 10-year Treasury bond simply means the US government is borrowing money for 10 years.
The "yield" is the return an investor earns for lending that money. Here is the one tricky part worth understanding carefully. Bond prices and bond yields move in opposite directions. When more investors want to sell their bonds, or fewer people want to buy new ones, bond prices fall. When bond prices fall, the yield automatically goes up. When many investors want to buy bonds, prices rise, and the yield goes down.
So when you hear that the 10-year yield is rising, it simply means investors are demanding a higher return to lend money to the US government. This usually happens when investors are worried about inflation, expect interest rates to stay high for a while, or simply have other places where they can earn a similar or better return.
Why this one number matters so much to the whole world
US government bonds are seen as one of the safest investments anywhere in the world, since they are backed by the US government. Because of this safety, the 10-year yield acts like a baseline number, a kind of "safe return" that every other investment in the world gets compared against.
Picture this from the point of view of a large global investor. If a very safe, government-backed US bond is paying more than 5 percent a year, with very little risk, then any other investment, including Indian stocks, needs to offer a good enough reason to take on more risk. When this safe baseline number goes up, it raises the bar for everything else in the world, including the stocks you may be holding.
What is actually happening right now, and why
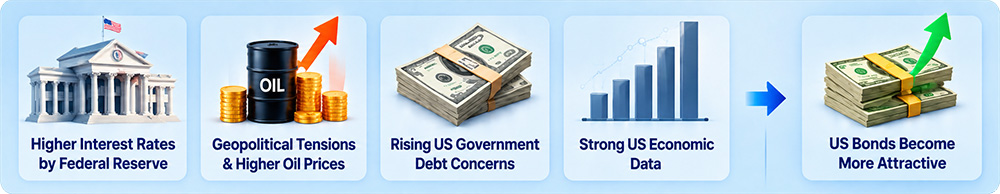
The 10-year yield has climbed above 5 percent recently, and even touched levels above 5.3 percent at one point. A few real reasons are behind this rise. The US central bank, called the Federal Reserve, raised interest rates in September. There is also continued tension in the Middle East, which has kept oil prices high. On top of that, there is growing worry about how much debt the US government itself carries, and recent US economic data has stayed strong enough that the Federal Reserve feels no urgent need to cut rates. The Federal Reserve currently keeps its own key interest rate between 3.75 percent and 4 percent, and since inflation in the US is still a bit above their target, there is limited room for them to cut rates soon.
All of this together has made US bonds more attractive to investors around the world. A safe investment paying more than 5 percent a year is simply a hard return to ignore.
How this number actually reaches your Indian portfolio
Here is the full chain, explained one step at a time.
First, foreign investors start pulling money out of markets like India. When US bonds offer such a strong and safe return, large global investment funds, the kind that invest money across many different countries, start moving money back toward the US. In India, this shows up directly as what is called FII selling, short for Foreign Institutional Investor selling. This is not just a theory. It is exactly what has been happening in recent weeks, and it is one of the key reasons behind the Nifty's long falling streak.
Second, the Indian rupee becomes weaker. When foreign investors sell their Indian stocks, they usually convert their rupees back into dollars to invest elsewhere. This increases demand for the dollar compared to the rupee, which weakens the rupee. This is part of the reason the US dollar has recently been trading around 95 to 96 rupees. A weaker rupee has its own effects too. It makes imports, including crude oil, more costly for Indian companies, while it can actually help Indian exporters who earn money in dollars and then convert it back into rupees.
Third, Indian bond yields often rise too. When US yields climb, Indian bond yields usually move up as well, since Indian bonds also need to offer a good enough return to hold on to investors who could otherwise park their money safely in the US instead. Higher bond yields in India often mean higher borrowing costs, both for companies and for regular people taking loans.
Fourth, investors start reconsidering what stocks are actually worth. When the safe return available elsewhere goes up, investors naturally become more careful about which stocks deserve their money, especially stocks priced on the assumption of a lot of future growth that has not actually happened yet. This is one reason stocks with very high valuations often feel more pressure during times when US yields are rising.
Which parts of your portfolio feel this the most
Export-focused sectors, like IT companies, feel a mixed effect. A weaker rupee can actually help IT companies, since they earn most of their revenue in dollars and then convert it back into rupees. However, IT stocks have also been under separate pressure this year, for other reasons like worries about AI changing how the industry works, so this currency benefit alone has not been enough to fully offset that pressure.
Companies that have borrowed money in dollars feel this directly. If an Indian company owes money in dollars, a weaker rupee makes that debt more expensive to repay once converted back into rupees.
Stocks priced for a lot of future growth tend to be more sensitive. These stocks are often valued based on profits that are expected many years into the future. When the safe return available elsewhere rises, those future profits become worth comparatively less in today's terms, since investors naturally compare future gains against this higher baseline return.
Sectors that depend heavily on imported oil face a double pressure. A weaker rupee, combined with high crude oil prices, which have also been a factor behind recent market pressure, raises costs for companies that rely a lot on imported oil or oil-based materials.
What this does, and does not, mean for you
It is worth being very clear about what this actually means for your investments. A rising US yield does not mean Indian companies have suddenly become worse businesses overnight. It mainly means that the competition for investor money around the world has become tougher, and the price investors are willing to pay for the exact same business can shift, even when nothing has actually changed inside that business. This connects back to something we have talked about before, the difference between owning a company and simply watching a stock price. A stock reacting to global yield movements is often about money moving around the world and valuation calculations shifting, not necessarily a sign that the company itself has done something wrong.
It also helps to remember that this situation is not permanent. US yields move in cycles, based on central bank decisions, inflation numbers, and global events. Once the Federal Reserve eventually cuts rates again, or once some of today's pressures, like the Middle East tensions or debt worries, start easing, this pattern can reverse. Foreign investors have returned to Indian markets many times before, once global conditions shift in a more favourable direction.
A number from the US bond market reaches all the way into your portfolio through a fairly simple chain of events. Higher US yields make safe US investments more attractive, which pulls foreign money out of India, weakens the rupee, and makes investors rethink how much they are willing to pay for Indian stocks, especially the ones priced heavily on future growth. None of this means Indian companies themselves have suddenly become weaker businesses. It mainly reflects where global money is choosing to flow at this moment, and that choice shifts as US interest rates, inflation, and world events shift too. Understanding this one connection, between a number most people only notice in financial headlines and the daily movement inside their own portfolio, is a genuinely useful habit for any long-term investor to build.