Before you buy a stock, there is a simple question that most investors never ask. Who else owns this company, and are they buying or selling? The answer sits in a table that every listed company files with the stock exchanges each quarter, called the shareholding pattern. Companies must file it within 21 days of the end of the quarter, which means the filings for the quarter ended September 30 are due by October 21.
The filing divides the owners into three broad blocks. The first is the promoter and promoter group, which means the founders or the controlling shareholders, their relatives and their group companies. The second is the public, which has several parts. One part is institutions, divided into domestic institutions and foreign institutions. A second part is the government. The third part is non institutions, which includes individual investors, non-resident Indians, companies and trusts. The third block is a small category of shares that belong neither to the promoters nor to the public, such as shares held by employee trusts or by custodians for depository receipts. In everyday market talk, the groups are shortened to four names: promoters, FIIs, DIIs and the public. FIIs are foreign institutional investors, which the filing calls foreign portfolio investors. DIIs are domestic institutional investors, such as insurance companies, banks, pension funds and the funds run by domestic asset managers. The public in everyday talk means retail investors and the other non-institutional holders.
Promoters, the owners who run the company
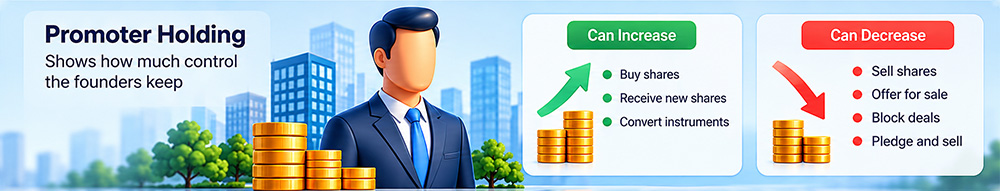
The promoter holding tells you how much control the founders or the controlling family keep. A high holding usually means that the owners have a large stake in the success of the company, and a low holding means that the company is widely held. Neither is good or bad on its own. What matters is the trend and the reason for it. Promoters can raise their stake by buying shares in the market or by receiving new shares, and they can lower it by selling shares through an offer for sale, through block deals or by pledging and selling to repay loans. A fall in the promoter holding is not always a negative sign. Promoters may sell to meet the rule that the public must hold at least 25 percent of the company, to reduce debt, or simply because valuations are high. One should always ask why a promoter is selling and at what price.
A promoter percentage can also change without a single share being sold. If the company issues new shares, as in a QIP, the total number of shares rises and the promoter percentage falls. This is why it is worth checking the share count along with the percentage. Also look at who the promoter is. In public sector companies the government is the promoter, and in some listed companies there is no promoter at all, so the table shows zero, and then it is more useful to look at the largest institutional holders.
FIIs, foreign money that follows global conditions
Foreign portfolio investors invest in Indian shares from outside the country, and they tend to hold large stakes in the biggest and most liquid companies, especially in banks, IT and large conglomerates. Their holdings change with global conditions such as US interest rates, the strength of the dollar and risk appetite around the world, and not only with the news about a particular company. We saw this in our article on US bond yields, where higher US yields pulled money away from Indian shares. A rise in FII holding means that foreign institutions have been adding the stock, and a fall means that they have been selling, but the reason may lie outside the company.
A stock with a high FII share can be more sensitive to global flows, both on the way up and on the way down. A stock with a low FII share has less exposure to such swings, although this does not mean that foreign buying will arrive later.
DIIs, domestic institutions
Domestic institutions invest the savings of Indian households and businesses, and their share of the Indian market has been rising, while FIIs had reduced their holding. This is the structure behind a pattern that many of us have seen in the daily data, where domestic institutions buy shares that foreign investors sell. Domestic institutions can also sell, and a high DII holding does not guarantee that a stock will rise. What the DII line tells you is how much of the stock is held by domestic professional investors who research companies, and whether that share is rising or falling.
The public, retail and other investors
The public category contains retail investors, high net worth individuals, non-resident Indians, companies and trusts. In the filing, individuals who hold shares with a nominal value up to ₹2 lakh are counted as retail, and those above that limit are counted separately. The limit is based on the face value of the shares and not on their market value, so an investor with a large market value in a stock with a low face value may still be counted as retail. The public share is usually larger in smaller companies, and it is generally more sensitive to price movements and news. A rising public share while institutions are selling can mean that a stock has become popular after a rally, or that informed holders are leaving, and it is worth finding out which one it is.
The most useful reading comes from looking at the groups side by side over eight to twelve quarters and measuring the change in percentage points. When the promoters hold steady or buy and the foreign investors sell, as in the example above, the cause is often global flows, and the key question is whether the business is doing as expected. When promoters sell and institutions buy, shares are moving from insiders to professional investors, and you should check the price at which the promoters sold and the reason given. When both FIIs and DIIs are adding, a broad group of institutions likes the stock, but check whether the price has already risen a lot, because a good story that is widely known may already be in the price. When the public share rises while institutions fall, ask whether this is the early discovery of a small company or the late arrival of buyers after the institutions have taken profits. None of these patterns predicts what will happen next.
Pledged shares, the number that deserves a close look
Promoters sometimes pledge their shares to lenders as security for loans. In the shareholding pattern, you will find a section that shows the number of promoter shares that are pledged or otherwise encumbered, and the percentage of the promoter holding that this represents. The risk is simple. If the share price falls, the lender may ask for more security, and if the promoter cannot provide it, the lender can sell the pledged shares, which adds selling pressure at a time when the price is already weak. A high and rising pledge, especially when the business is under stress, is a warning sign. A low or zero pledge is a cleaner picture. Check the trend over several quarters and the reason for the loan, since a loan used for the business is different from one used for another purpose.
Why the public must hold at least 25 percent
Under the rules for listed companies, at least 25 percent of the shares generally have to be held by the public, with some exceptions and time limits for certain companies, which means that promoters can hold at most about 75 percent. In the June 2026 quarter, one listed company showed a promoter holding of 73.15 percent, which is close to this ceiling. A company near the ceiling has little room to issue shares to promoters, and it may use an offer for sale or a QIP to raise the public holding or raise capital. This is one more reason why changes in the promoter percentage need to be read with the news about the company.
What the pattern cannot tell you
The shareholding pattern is a snapshot taken on one day each quarter and published about three weeks later, so it does not show the buying and selling that took place inside the quarter. A quarter appears in the data only after the company has filed it, so the latest quarter shown on a website may lag the calendar. For faster information, look at the bulk and block deal data and at the disclosures that promoters and directors must make when they trade above certain limits. Also remember that different websites classify groups differently, that a holding in percentage terms can change when the share count changes, and that the table says who owns the shares but not why. The reasons must come from the news, the filings and the concall.
A simple routine to follow each quarter
When a new shareholding pattern is filed for a company you own or follow, open the exchange filing and record the promoter, FII, DII and public holdings for the last eight quarters in a simple sheet. Calculate the change in percentage points for each group, and note the pledged share of the promoter holding and the number of shareholders. Compare the picture with two or three peers, since a pattern that looks unusual may be normal for the sector. Then find the reason for any large change in the news, the exchange announcements and the concall transcript, and add it to your research on earnings, valuation and the business. The table below is a made up example, to show how such a sheet might look.
| Quarter | Promoters | FIIs | DIIs | Public |
|---|---|---|---|---|
| September 2025 | 54.0 | 14.0 | 17.0 | 15.0 |
| December 2025 | 54.0 | 13.2 | 17.8 | 15.0 |
| March 2026 | 53.5 | 12.6 | 18.7 | 15.2 |
| June 2026 | 52.8 | 11.9 | 19.9 | 15.4 |
| September 2026 | 52.8 | 11.5 | 20.5 | 15.2 |
In this example, promoters reduced their holding by 1.2 percentage points over four quarters and then held steady. FIIs lowered their holding by 2.5 percentage points and DIIs raised theirs by 3.5, so domestic institutions absorbed the foreign selling. The questions to ask are why the promoters sold, at what price, whether the foreign selling reflects global flows or concerns about this company, and whether the rising DII holding is supported by the earnings and valuation. The sheet gives you the questions and your research supplies the answers.
Mistakes to avoid
The first mistake is to follow the FIIs or the DIIs blindly, since institutions can be wrong and can sell as quickly as anyone else. The second is to treat promoter selling as always bad or promoter buying as always good, without checking the price, the reason and the pledge. The third is to ignore the pledged shares. The fourth is to compare the shareholding of companies from very different sectors as if the numbers meant the same thing. The fifth is to forget that percentages change when new shares are issued. The sixth is to depend on one quarter instead of looking at the trend, and the seventh is to use the data from a website without checking it against the filing. This article is for education and is not a recommendation to buy or sell any stock, and every stock market investment carries risk.
The shareholding pattern shows who owns a company and how that ownership is changing. Promoters tell you about control and confidence, FIIs about global money, DIIs about domestic institutional interest and the public about retail participation, and the pledged shares add a risk check. None of these numbers can predict the price, but together they give you good questions to ask about the business. Read the last eight quarters, measure the changes in percentage points, compare with peers, find the reason behind each large move, and use the result as one input to your research. With the filings for the September quarter arriving now, it is a good time to start.