An IPO has its own language. You hear about the anchor book, the price band, the cut off price, the lot size and the retail quota, and many investors apply without being sure what each of these means for their money. This is a good week to learn them, because the largest IPO in Indian history is open right now, and every term in this article can be seen in it. The issue is a ₹30,213 crore fresh issue with a price band of ₹1,065 to ₹1,119 and a lot size of 12 shares, and it opens on October 21 and closes on October 23. In this article, we use the numbers from this issue as a worked example, without recommending it, and explain step by step how an IPO application works and what to check before you press the button. All dates here are tentative and the final word is the red herring prospectus and the exchange notices.
The timeline from the point of view of an investor
An IPO runs on a fixed calendar, and knowing the calendar avoids most mistakes. First the company files the red herring prospectus, and announces the price band. In this issue, the RHP was filed and the price band approved on October 14. A day before the issue opens, the company allots shares to anchor investors, and in this case the anchor bidding was on October 19. Then the public issue opens for three working days, during which retail, non-institutional and institutional investors place their bids. After the close, the registrar prepares the basis of allotment, the shares are credited to the demat accounts of successful applicants, the blocked money of the others is released, and the shares list on the exchanges. The timetable below shows the dates for this issue.
| Event | Date |
|---|---|
| Anchor bidding | October 19 |
| Issue opens | October 21 |
| Issue closes | October 23 |
| Basis of allotment | October 26 |
| Refund and credit of shares | October 27 |
| Tentative listing on NSE and BSE | October 28 |
The dates after allotment are tentative and subject to regulatory approvals. The listing comes three working days after the close of the issue, which is the standard timeline in India, often called T+3.
What the price band means
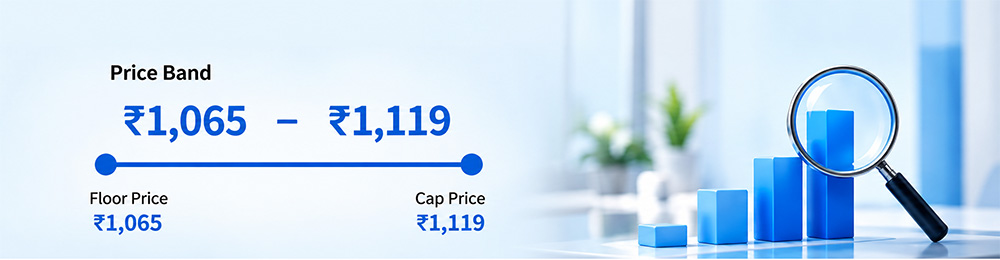
An IPO in India is usually sold by a process called book building. The company does not announce one fixed price. It announces a range, called the price band, which has a floor price at the bottom and a cap price at the top. In this issue, the floor price is ₹1,065 and the cap price is ₹1,119. Investors place bids within this range, and the company and its lead managers study the bids and decide the final issue price after the issue closes. This final price is called the issue price, and it can be anywhere in the band. If demand is strong, the issue price is usually the cap. Under the ICDR rules, the cap price can be at most 20 percent above the floor price, and the band must be announced at least two working days before the issue opens, so that investors have time to decide. In this issue, the cap is only about 5 percent above the floor, which is a narrow band, so the amount at stake between the lowest and highest price is small. The issue is described as 100 percent book built. The price band gives you the range in which you can bid, and the final price is not known until the bidding has closed.
Lot size and how much you need
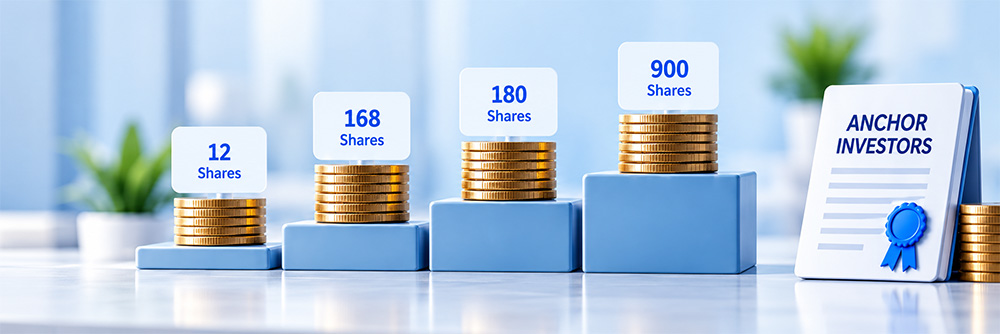
You cannot bid for a single share. Shares are sold in lots, and the lot size is fixed in the prospectus. In this issue, one lot has 12 shares, so the minimum investment is ₹13,428 at the upper price, which is 12 shares multiplied by ₹1,119. At the floor price, the same lot costs ₹12,780. Your bid must be in multiples of the lot size, for example 12, 24, 36 shares, and so on. The amount you can bid also decides the category in which your application falls. Individual investors whose total bid is up to ₹2 lakh are counted as retail investors. The retail maximum in this issue is 14 lots, or 168 shares, which is ₹1,87,992 at the upper price. A bid of 15 lots comes to ₹2,01,420, which is above ₹2 lakh and falls into the small non institutional category, and the big non institutional category starts at 75 lots, or ₹10,07,100. The table below shows the main application sizes at the cap price.
| Application | Lots | Shares | Amount at ₹1,119 |
|---|---|---|---|
| Retail minimum | 1 | 12 | ₹13,428 |
| Retail maximum | 14 | 168 | ₹1,87,992 |
| Small non institutional minimum | 15 | 180 | ₹2,01,420 |
| Big non institutional minimum | 75 | 900 | ₹10,07,100 |
The category matters because each category has its own share of the issue and its own allotment method. Under the usual structure, qualified institutional buyers get not more than 50 percent of the net offer, non-institutional investors get at least 15 percent and retail investors get at least 35 percent. Some issues also reserve part of the shares for employees and for shareholders of a parent company. In this issue, up to 46,94,835 shares are reserved for employees, who get a discount of ₹54 to the issue price. Read the allocation table in the prospectus, since the reserved portions reduce what is left for the rest.
Who the anchor investors are, and why they come first
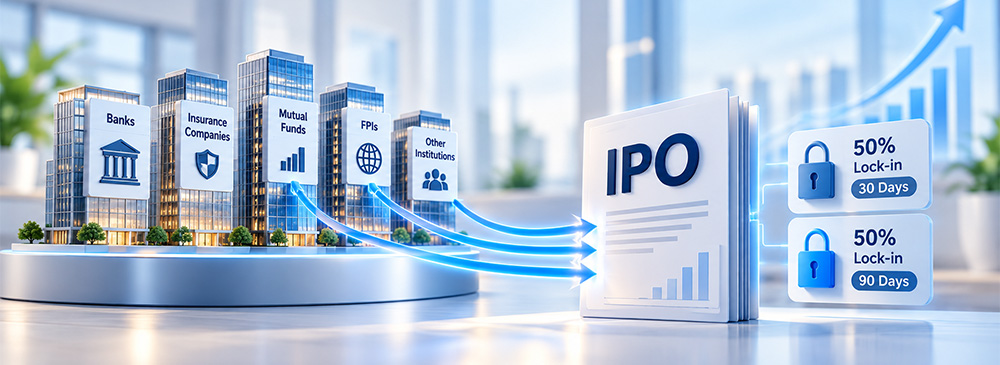
Anchor investors are large institutions that are allowed to buy shares in the IPO a day before it opens to the public. They are qualified institutional buyers, which means banks, insurance companies, foreign portfolio investors and similar institutions, and they must bid a minimum amount. Under the rules, up to 60 percent of the portion set aside for qualified institutional buyers can be given to anchor investors, and the company and its bankers fix the anchor price, which is usually the cap of the band. The anchor allotment is announced before the issue opens, together with the names of the investors. On October 19, this company raised ₹8,109.85 crore from 212 anchor investors, allotting 7.24 crore shares at the upper price band of ₹1,119. That is about 27 percent of the whole issue. Reported institutional demand in the anchor book was more than ₹2.5 lakh crore.
Why do anchors exist? They give the market an early signal. When well-known institutions with a long term record bid at the top of the band before the issue opens, other investors take it as a sign of confidence, and this can reduce the risk that the issue fails. The anchor allotment also fixes a large part of the book before the public bidding begins. To make sure that anchors are real long term holders and not quick sellers, their shares are locked in. Half of the shares allotted to an anchor investor are locked in for 30 days and the other half for 90 days from the date of allotment. If allotment is on October 26, the first half could be sold on the exchange from about November 25 and the second half from about January 24, 2027, so the supply of shares in the market can rise on those dates, and you should add them to your calendar.
It is important to read the anchor signal correctly. Strong anchor demand tells you that large institutions like the issue at this price. It does not guarantee a gain on listing, and it does not tell you that the price is low compared with the business. The reported demand is also not the same as the shares allotted, since the book was far larger than what the anchors received. Use the anchor list as one more input, together with the valuation and the quality of the business that you have studied in the prospectus.
What the cut off price is
When you place a bid, you can choose to bid at a specific price within the band or at the cut off price. Bidding at the cut off price means that you agree to pay the final issue price, whatever it turns out to be within the band. In practice, the cut off price is the cap of the band, so in this issue retail investors can choose the cut off price, which is the upper end of the band at ₹1,119. Only retail individual investors and employees can use this option. Non institutional and institutional investors must bid at a specific price.
There are two reasons why retail investors usually choose the cut off price. First, a bid at the cut off price is valid at any final price in the band, so it cannot be rejected because the final price came out higher than your bid. A bid below the cap is valid only if the final price turns out to be at or below it. Second, the money is blocked at the cap price, so you do not have to guess. Your bank blocks the upper band amount until allotment. If the final price is lower than the cap, the difference is released. For example, if the issue price is fixed at ₹1,100, a successful applicant for one lot pays ₹13,200 and the remaining ₹228 of the blocked ₹13,428 is unblocked. The cut off option makes the process simple, but you must be comfortable paying the top of the band, because in a strong issue that is the price you will pay.
How the application works step by step
To apply, you need a demat account and a bank account linked to a UPI ID. You open the IPO section of your broker app or your bank, select the issue, choose the category and enter the number of lots. Then you either enter a price within the band or tick the cut off option. After that, you enter your UPI ID, and a mandate request arrives on your UPI app, which you must approve before the time limit. The amount is blocked and not debited until allotment. This facility is called ASBA, which means that the money stays in your own account while it is blocked, and you keep earning interest on it. Check that the application shows as successful and note your application number. Apply on the first or second day if you can, and not on the last day, since the last day often has delays in apps and bank systems, and the mandate can fail.
Each investor can place only one application per PAN in a category. Applications for family members are separate, and each one must be made with the PAN, the demat account and the bank account of that person. Some investors apply for a single lot across several family accounts in the expectation that heavy demand will make allotment a lottery. If you do this, each applicant must use his or her own funds and accounts, and you should not borrow to apply.
What happens after the issue closes
After the close, the registrar adds up the bids in each category and calculates how many times the shares on offer were subscribed. If a category is subscribed less than once, all valid bidders get what they asked for, subject to the rules. If it is subscribed many times, shares are allotted according to the rules for that category. In the retail category, when the issue is heavily oversubscribed, there are not enough shares to give every applicant even one lot, so allotment is made by a computerised draw among the valid applications, and each successful applicant normally gets the minimum lot. This is why applying for more lots does not raise your chance of getting shares in a heavily oversubscribed retail category. It only locks up more of your money for the same chance.
The unsuccessful bids are unblocked, successful bidders receive the shares in the demat account, and the listing follows.
What to decide before you apply
Applying for an IPO is a decision to buy a business, and your plan should be ready before you place the bid. Read the red herring prospectus, using the method from our earlier article, and check the objects of the issue, the financials, the valuation and the lock in dates. Decide how much you can invest and keep it within the part of your money that you are prepared to leave in equity for a long time. Choose your category and your bid, and decide whether you will bid at the cut off price. Decide in advance whether you plan to hold the shares for the long term or sell soon after listing, and what would make you change your mind. A plan that is written before the excitement of listing day helps you avoid decisions made on emotion. Also keep in mind that you may not be allotted any shares, so do not count on the money you have blocked as already invested.
Mistakes to avoid
The first mistake is to bid below the cap in the hope of a lower price, and to find that the bid is not valid when the final price is higher. The second is to apply at the last minute, when apps and UPI systems can fail. The third is to forget to approve the UPI mandate, in which case the application is not complete. The fourth is to choose the wrong category, for example by bidding 15 lots and being placed outside the retail category. The fifth is to assume that a strong anchor book guarantees a listing gain. The sixth is to rely on the grey market premium. The seventh is to apply for more lots in the hope of a better chance of allotment in a heavily oversubscribed retail category. The eighth is to borrow money to apply. The ninth is to ignore the lock in expiry dates of anchors and other holders. The tenth is to apply without a plan for what you will do on listing day. This article is for education and is not a recommendation to apply for any IPO, and every investment in the stock market carries risk, including the risk of loss of capital.
An IPO application is simple once you know the terms. The price band is the range in which you can bid, and the issue price is decided after the bids come in. The lot size fixes the minimum amount and, with the amount you bid, your category. Anchor investors are large institutions that buy a day earlier and are locked in for 30 and 90 days, and their demand is a signal and not a guarantee. The cut off price means that you accept the final price in the band, and the amount at the cap is blocked in your account until the allotment. After that, a heavily oversubscribed retail category is decided by a draw, so applying for more lots does not raise your chance. Read the prospectus, decide on your amount and your plan before you bid, and treat the listing day as the start of owning a business and not as the end of the process.